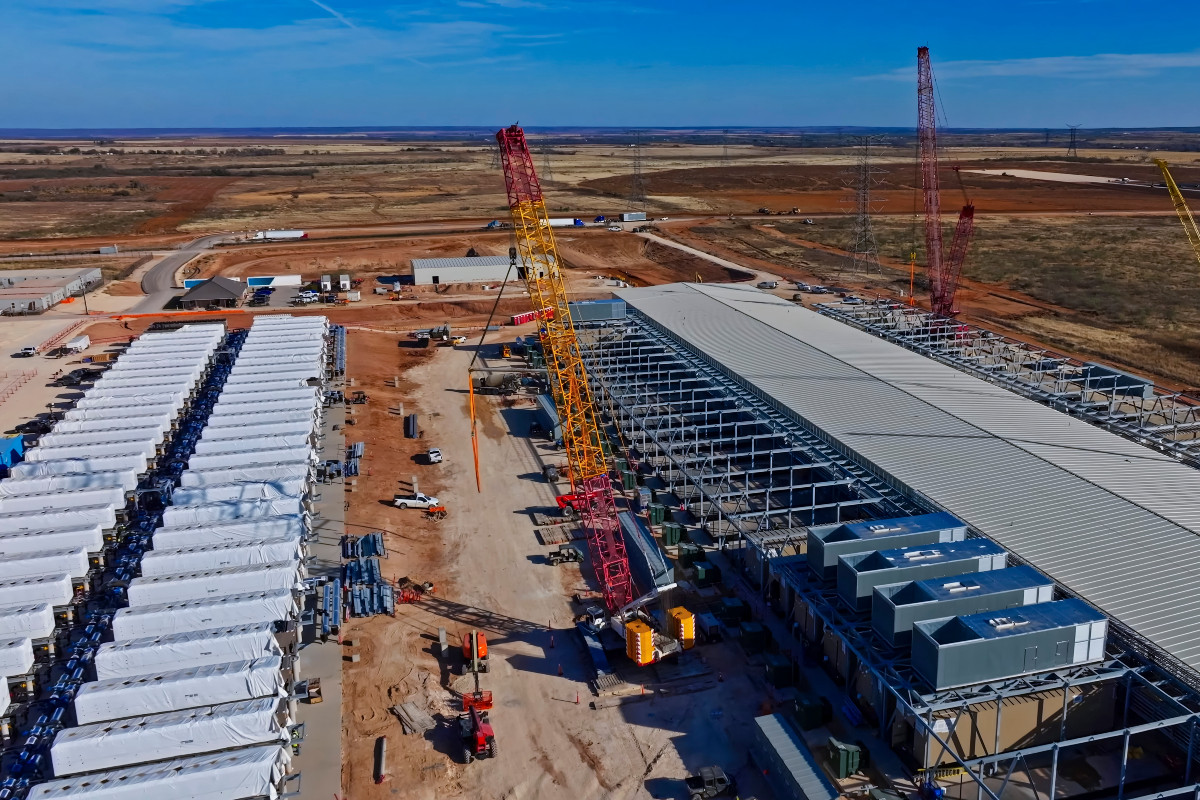
While it may seem that not a day goes by where there isn’t a new data centre proposed for the UK, the country is actually expected to have one of Europe’s slowest rates of data centre demand growth up to 2030.
That’s according to new research from consultancy Kearney, which projects annual growth of 17.6% for the UK, placing it 18th out of 19 European markets analysed, ahead of only Germany at 16.2%. Compare that to Ireland where growth is forecast to reach 36% annually, while Finland and Norway are estimated to lead Europe at 37.6% and 36.8% respectively, you can see the problem the UK faces.
The figures measure growth in Kearney’s composite demand index, which draws on indicators including cloud adoption, AI activity and existing market demand, rather than the amount of new data centre capacity expected to come online.
That’s an important distinction because previous reporting has shown significant constraints when it comes to vacancy rates in areas like Frankfurt, London, Amsterdam, Paris and Dublin. That means there’s still clearly demand for data centre space – but given they’re more established markets, they’re likely to grow at a slower pace.
In fact, Kearney highlighted exactly that. It estimates that the UK, Germany and France will collectively account for 32.1% of the projected increase in index points across the 19 markets, despite being amongst the slowest growing when it comes to a percentage basis.
Power and land costs threaten UK competitiveness
While that establishes the fact that the UK’s market is still growing, Kearney believes it’s possible that the market would grow faster if it wasn’t facing significant constraints related to electricity.
It’s well-established that getting a grid connection or simply securing enough electricity is not an easy task in the UK, and Kearney estimates that the cost of land with an established grid connection costs approximately €2.25m to €2.30m per MW across Europe’s established western markets, compared with €0.6m to €0.8m in leading Nordic locations. This is one of the reasons cited behind OpenAI’s decision to scrap its Stargate plans in the UK.
JLL’s latest European data centre research also suggests that high-power AI training workloads are increasingly moving towards locations where electricity is more readily available, while latency-sensitive workloads continue to favour established hubs such as London.
The findings will still be awkward reading for the UK Government, which is still attempting to accelerate domestic AI infrastructure development as it hopes to remain competitive against both China and the United States.
Its Compute Roadmap forecasts a requirement for at least 6GW of AI-capable data centre capacity by 2030, while AI Growth Zones are intended to streamline planning and improve access to power.
However, recent analysis of planning activity within designated AI Growth Zones suggests that the policy has yet to deliver a significant acceleration in development.
Christoph Neunkirchen, Partner and Kearney’s European Data Centre Lead, noted, “The UK doesn’t have a relevance problem; it has a selectivity problem. Demand, connectivity, and operators are already there, and none of that is in question.
“What has changed is that power and land are scarce enough that the next wave of capacity must match the workloads that genuinely need to be close to users, customers, and national jurisdictions. Everything else will go where it is easier to build.”